Vikram, 36, bought a ₹75 lakh term plan when he was 28, single and earning ₹9 lakh a year in Bengaluru. It felt like plenty at the time. Eight years later, he is married with two children, has an ₹80 lakh home loan and earns ₹24 lakh a year. He hasn’t looked at his policy once since buying it. On paper, he is insured. In reality, his cover wouldn’t even clear the house.


Term insurance is often treated as a one-time decision. Your life doesn’t stay still, though, and the cover you bought years ago was sized for a very different version of you.


Why Does A Policy That Was Right Then Fall Short Now?


Two things work against an old policy. The first is that your responsibilities grow. Marriage, children, loans and supporting parents all raise the amount your family would need.


The second is inflation. At 6% a year, Vikram’s ₹75 lakh today buys roughly what ₹47 lakh would have bought when he took the policy. To match the buying power he started with, he’d need about ₹1.2 crore. The sum assured stays the same, but what it can pay for shrinks every year.


What Does Vikram’s Number Look Like Today?


Here’s a rough estimate. His household spends about ₹1 lakh a month, so 15 years of expenses come to ₹1.8 crore. Add the ₹80 lakh home loan and ₹25 lakh each for his two children’s education. Subtract ₹20 lakh of savings and investments he already has. His family would need about ₹2.9 crore.


Against that, his ₹75 lakh policy leaves a gap of about ₹2.15 crore. The estimate ignores investment returns and future inflation, so treat it as a starting point rather than a final figure. Even so, the gap is too large to explain away.


How Often Should You Sit Down And Review It?


A good habit is to review your cover every two to three years, even if nothing major has changed. It doesn’t take long. Note your current income, monthly household expenses, outstanding loans and your children’s ages, then compare what your family would need today with the cover you actually hold.


A term insurance calculator makes this quick. You can enter your current details and see where the number lands in a few minutes.


Which Life Events Should Trigger A Review Right Away?


Some changes are too big to wait two years. Getting married, having a child, taking a home loan or a large jump in salary are the most common. Starting a business, co-signing a loan for a family member, or parents becoming financially dependent on you also count. Each of these raises what your family would need, so review your cover within a few weeks of the change, not years later.


Can You Increase Cover On Your Existing Policy?


Usually not, unless your policy came with that option built in. Some term plans let you raise cover at certain life events, such as marriage or the birth of a child, often without new medical tests. If yours does, use it within the window the policy allows.


If it doesn’t, the simplest fix is a second term policy for the gap. Holding two or more policies is perfectly normal, as long as you disclose your existing cover when you apply. The new insurer will look at your total cover across both policies against your income. For Vikram, ₹2.9 crore in all is about 12 times his salary.


Found a gap in your own review? Look at term plans for the shortfall only, since your existing policy stays in place.


Mention your current policy on the proposal form, so the new insurer sees the full picture from the start.


Should You Ever Replace An Old Policy With A New One?


In most cases, no. Your older policy was priced on your age and health when you bought it, so it’s usually cheaper than a new one for the same cover.


It has another advantage. Under Section 45 of the Insurance Act, 1938, once a policy has run for three years, the insurer generally can’t call it into question on the grounds of what was in the proposal form. A new policy starts that three-year clock again. Keep the old policy running and add a new one on top.


What If Your Review Says You Need Less?


Reviews don’t only point one way. If your loans are paid off, your children are financially independent and your spouse has enough savings or income of their own, your family may need less cover than before. In that case, the sensible move is usually not to add anything.


Dropping an existing policy is a bigger decision. Term plans usually pay nothing back if you stop paying premiums, and you may not get the same price again if your needs rise later. Think it through carefully before letting one lapse.


What Else Should You Check Besides The Cover Amount?


A review is a good time to tidy up the details. Make sure the nominee is still the right person, especially after a marriage or the birth of a child. Check that your phone number, email and address are current with the insurer, and that the premium auto-debit still points to an active bank account. Look at your riders too, and ask whether you still need each one or whether something important is missing.


What Should You Do This Week?


Find your policy document, note the cover amount and the nominee, and run your current numbers. If there’s a gap, add a policy rather than replacing the one you have. Then set a reminder to repeat the exercise in two years, or sooner if your life changes. The policy that protected the 28-year-old won't automatically protect the family you have now.


The article first appeared on The Kashmir Pulse at https://kashmirpulse.com/business-economy/finance/how-often-should-you-review-your-term-cover-after-buying-it/117167.html
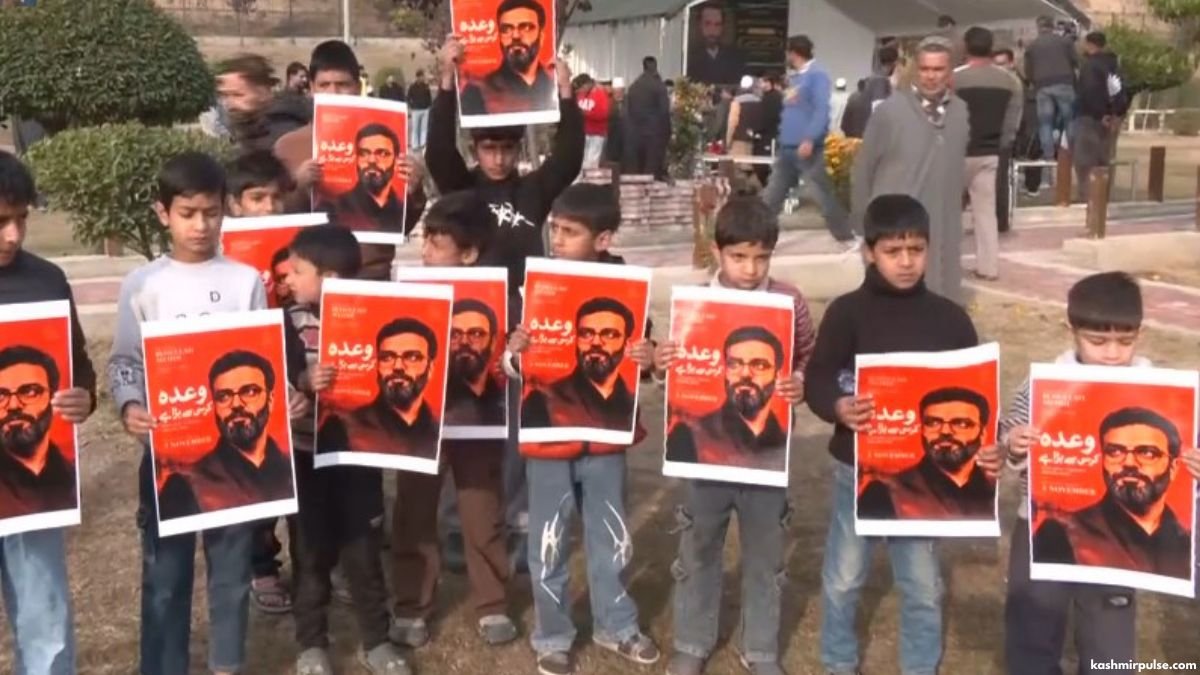

BUDGAM — Preparations intensified in Budgam on Sunday ahead of Srinagar Lok Sabha MP Aga Syed Ruhullah Mehdi’s announcement that he intends to resign from Parliament and the Jammu and Kashmir National Conference (JKNC) on November 3, amid growing tensions within the ruling party.


Mehdi is scheduled to address a gathering at Behisht-e-Zehra Park in Budgam on Tuesday, coinciding with the death anniversary of his late father, Aga Syed Mehdi, where he is expected to formally act on his previously announced decision.


The MP has accused the National Conference leadership of failing to fulfil its election promises, particularly those concerning the restoration of Article 370, the release of prisoners and the protection of people's rights.


Speaking to reporters, Mehdi rejected suggestions that his decision was linked to personal grievances or any alleged horse-trading within the party.


“November 3rd marks the death anniversary of my late father, and on that very day, the resignation that was previously announced will be carried out. Please do not associate me with any potential 'horse-trading' that might occur within the National Conference. I neither desire nor support horse-trading,” he said.


“My struggle is based on principles. It stems from the fact that the promises and assurances the National Conference gave to the people during the elections have not been fulfilled or acted upon. I have not been deprived of any position; I harbour no personal grievance over failing to secure a specific post or office,” he added.


In a statement issued by his office, Mehdi also accused the party leadership of treating Jammu and Kashmir as a family estate and betraying the promises on which it had sought public support.


The statement said the party had sought votes on commitments including the restoration of Article 370, the release of prisoners and protection of people's rights, but had failed to act on them.


“There is no fixing this rot from within,” the statement said, adding that Mehdi would surrender his Lok Sabha seat rather than become an accomplice to what it described as the betrayal of the promises made to voters.


The developments prompted political reactions, with Jammu and Kashmir Minister Javed Rana saying Mehdi's departure would not affect the party.


“If Aga Sahab decides to part ways, he will do so alone. If he leaves, he leaves by himself... Why would it affect the party?” Rana said.


He denied any resentment within the National Conference and maintained that the party remained united under its leadership.


“The JKNC is strong, the government under the leadership of the Chief Minister is robust, and the organisation, under the leadership of Dr Farooq Sahab, stands firm, as solid as a rock,” he said.


Meanwhile, locals gathered at Behisht-e-Zehra Park ahead of Mehdi's scheduled address, with some expressing support for his decision.


A local resident from Wahipora told ANI that people had assembled after receiving a call from Mehdi and were awaiting his announcement.


“We have come because Aga Sahib called us to gather here at Behisht-e-Zehra Park in Budgam today. We have heard that Aga Sahib is going to make a major decision in his life. Whatever that will be, it will be made public shortly in front of everyone,” the resident said.


He said he believed Mehdi's decision was driven by public commitments rather than personal interests and expressed support for the MP.


“Why wouldn't we stand with him? He speaks for us. If he were speaking for his own personal interests, we would not support him. Whatever decision he takes, we stand with him,” he added.


The proposed resignation marks a significant political development amid questions over internal differences within the National Conference following the party's time in government. However, Mehdi's resignation from the Lok Sabha and the party should be treated as pending until formally submitted and confirmed.


The article first appeared on The Kashmir Pulse at https://kashmirpulse.com/politics/aga-ruhullah-mehdi-set-to-resign-as-mp-quit-nc/117164.html


JAMMU — The All India Medical Students Association (AIMSA) on Monday urged the Jammu and Kashmir government to address the long-pending demands of Postgraduate (PG) resident doctors regarding revision of their stipend structure.


As per the news agency KNO, the association expressed concern over the existing stipend rates for PG medical and dental residents in the Union Territory, arguing that their remuneration does not adequately reflect their demanding clinical responsibilities, extended duty hours and contribution to patient care.


Addressing a press conference at Government Medical College (GMC) Jammu, the AIMSA representatives highlighted the disparity between the stipends paid to PG resident doctors in Jammu and Kashmir and those offered in several other states, calling for an urgent revision of the existing structure to ensure fair and competitive remuneration.


The press conference was addressed by AIMSA Chief Advisors Dr Sanah, Dr Abhishek Mittal, Dr Fazan Lone and Dr Sidhant Sharma. Dr Danish Hamid, Joint Secretary of AIMSA, represented PG dental residents across Jammu and Kashmir and highlighted the dental resident fraternity's concerns and demands. Dr Shahnawaz Malik, the association's Additional Secretary, was also present.


AIMSA representatives pointed out that PG resident doctors in Jammu and Kashmir currently receive a stipend of Rs 64,000 during their first year and Rs 67,000 in subsequent years, raising questions over the disparity with the remuneration offered to resident doctors in several other states.


They maintained that postgraduate residents play a crucial role in the functioning of government medical colleges and associated hospitals, where they are actively involved in patient management, emergency services, ward duties and other essential clinical responsibilities.


The association stressed that the demanding nature of postgraduate medical training requires residents to work for extended hours while balancing academic commitments with clinical duties. It said their financial concerns should be addressed through a fair and transparent stipend policy.


Seeking government intervention, AIMSA submitted a representation to Chief Minister Omar Abdullah, urging him to intervene and ensure an early resolution of the issue.


The representation was signed by AIMSA President Dr Mohammad Momin Khan, who sought the government's attention towards the concerns of PG medical and dental residents and called for a concrete decision on the long-pending demand.


The association has set November 12, 2026, as the deadline for the government to provide a concrete response and take steps towards resolving the stipend-related grievances.


AIMSA representatives said the demand was aimed at securing a fair and uniform stipend policy for postgraduate medical and dental residents in Jammu and Kashmir, in line with prevailing standards elsewhere in the country.


They maintained that addressing the issue would help acknowledge the contribution of resident doctors, who shoulder significant clinical responsibilities while undergoing specialised medical training.


The association further warned that failure to address the demands within the stipulated timeframe could compel its members to launch peaceful and democratic protests across Jammu and Kashmir.


The article first appeared on The Kashmir Pulse at https://kashmirpulse.com/health/aimsa-seeks-pg-doctors-stipend-revision-in-jk-sets-november-12-deadline/117162.html
Powered by Blogger.